Renegotiating the carrier relationship
Many of the largest marketplaces are no longer content to be the place where buyers and sellers meet. Increasingly, they’re looking to own the entire journey, from checkout to doorstep, emulating the FBA model we’ve come to know so well. Allegro in Europe, Walmart in the USA, JD.com in China – all are looking to control fulfilment operations as much as possible.
Equally, many marketplaces are deliberately leaving their logistics open. eBay keeps fulfilment in the seller’s hands and actually trialled an end-to-end delivery service before walking away. Etsy, another giant, offers no logistics at all; most of the smaller marketplaces are the same.
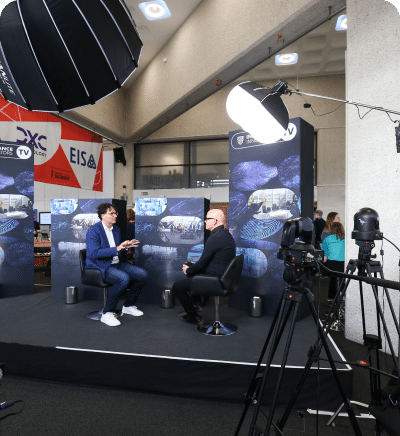
So, for sellers spanning multiple channels, this growing split is becoming a real headache, as carrier management becomes more fragmented and bargaining power increasingly weakened. This is an issue that attendees at March’s Leaders in Logistics Summit sat down to discuss in the Marketplace Logistics Forum workshop.
The session brought together marketplaces, e-commerce platforms, e-retailers and carriers to discuss how to effectively navigate the increasing complexity of carrier orchestration. Below are the headlines:
Getting the carrier mix right
Price has long been a critical factor in carrier selection, and this won’t change. What is changing, though, according to our delegates, is the growing need for resilience which usually costs more, and for which sellers are increasingly willing to pay. The logic is that, when you’re selling across multiple, varied channels, a balanced carrier mix that weighs cost, coverage and performance together beats chasing the lowest rate. A cheap carrier that fails an SLA costs you more downstream that it saved you upfront. Those who are able to take the longer view are increasingly opting for the balanced option.
Achieving that balance is easier said than done. One attendee made the point that managing a multi-carrier network across multiple destinations is a balancing act, demanding proactive, real-time coordination to keep everything aligned. The enabler, the room agreed, is visibility: without a single view across carriers, a seller can’t see which one is struggling until the complaints start rolling in.
SLAs: keeping the stick, adding the data
SLAs put sellers in a tough spot. The buyer holds them to the marketplace’s promised delivery standards, but they depend on a carrier that they only partly control.
Traditionally, sellers often attempted to solve this issue with punitive enforcement. Yet the delegates weren’t convinced by it. Punishing a carrier for inadequate performance, they said, may satisfy the contract, but it leaves the cause unfixed and customer satisfaction damaged. The better model keeps the rod but pairs it with transparency. The SLAs remain binding, and missing them continues to be penalised, but sellers’ expectations are communicated clearer, and shared resources, like scorecards, surface issues and help reduce them over time.
The transparency conversation then moved onto another vital topic. Who, actually, is responsible for an SLA breach – platform, marketplace, seller, or carrier? Often, the seller is caught in the middle. The marketplace and the carrier often have no direct contract, so when a delivery fails, it’s the seller being hit with the marketplace’s penalty. And the carrier? Their liability is typically capped at a fraction of what the breach costs the seller. On top of that, the seller shares the reputational brunt with the marketplace in the eyes of the buyer. That reputational exposure is a key reason why major platforms are looking to lock down fulfilment ecosystems. For sellers who want to continue to choose their carriers, and platforms that want to give them the option, closing the gap with clear contractual lines and the data to prove fault keeps an open ecosystem viable.
The orchestration layer
The discussion then turned from getting the best out of carriers to getting the best carrier for each shipment. For a multi-channel seller, the appeal of orchestration software is that it merges an array of integrations into one. Rather than managing each relationship by hand, you let the platform route each parcel to the right partner by rule. Some also offer aggregated rates through their own carrier agreements, but the main attraction is the cross-channel control sellers get through one integration.
As the biggest platforms keep pulling fulfilment in-house, sellers who want to keep their carrier choice will have to earn it, through the visibility, accountability and orchestration that make an open model as reliable as a closed one.
The takeaway
The message which appeared throughout the workshop was this: the carrier relationship can no longer be set and forgotten. The carrier mix, SLAs, accountability, orchestration – all are moving from fixed to actively managed arrangements, shaped by data and clear contractual agreements. Major platforms are building their own networks. Sellers can’t outbuild them alone, but through better orchestration they can pool the leverage to keep an open model every bit as reliable, and keep setting their own terms.
Rise to the challenge of marketplace expansion
Don't miss The Marketplace Logistics Forum at Leaders in Logistics: Autumn
Ready to talk?
Book a call with me.
Ellie Kennedy
Senior Business Development Executive,
Leaders in Logistics
Stay in the loop with Leaders in Logistics
Subscribe to our newsletter to receive news,
updates and special offers.
By submitting this form you agree to our Privacy Policy and Terms & Conditions